In an essay circulated through TechFlow on November 11, 2026, Multicoin’s Spencer Applebaum argued that frontier AI tools are collapsing the cost of writing DeFi software without collapsing the things that actually make a financial business valuable. The piece treats that gap as the next iteration of a long-running question inside the firm: how protocols capture value once code is easy to copy.
Five years earlier, Applebaum writes, a DEX or lending protocol typically meant raising about $3 million, hiring five engineers, and spending six months on a minimum viable product. By the time of the essay, a founder using tools such as Claude Code could assemble most of the framework in a weekend. A frontier model asked to build a perpetual-futures exchange could, in his account, generate a matching engine, a risk engine, a trading interface, an API, and most of the other core pieces nearly out of the box. Software construction costs were falling across categories. Financial services, he contends, remain among the hardest businesses to turn into a commodity, because their valuable parts have little to do with the software itself.
Loyal customers, a large balance sheet, and proprietary data plus underwriting skill take years of relationships, a track record, and trust. A model can write a lending protocol in an afternoon. It cannot produce $10 billion of stablecoin deposits flowing into that contract, or 28 million customers for a new internet broker. Applebaum’s premise is that DeFi continues to take share from centralized crypto venues and, eventually, from traditional finance, while the barriers that support high-value financial businesses do not get easier. He expects trillions of dollars of financial activity to move on-chain over the following decade. Cheaper products do not, in this telling, automatically hand the economics to today’s blue-chip protocols.
What the essay treats as evidence of the shift
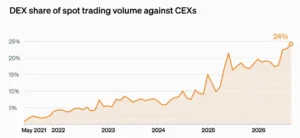
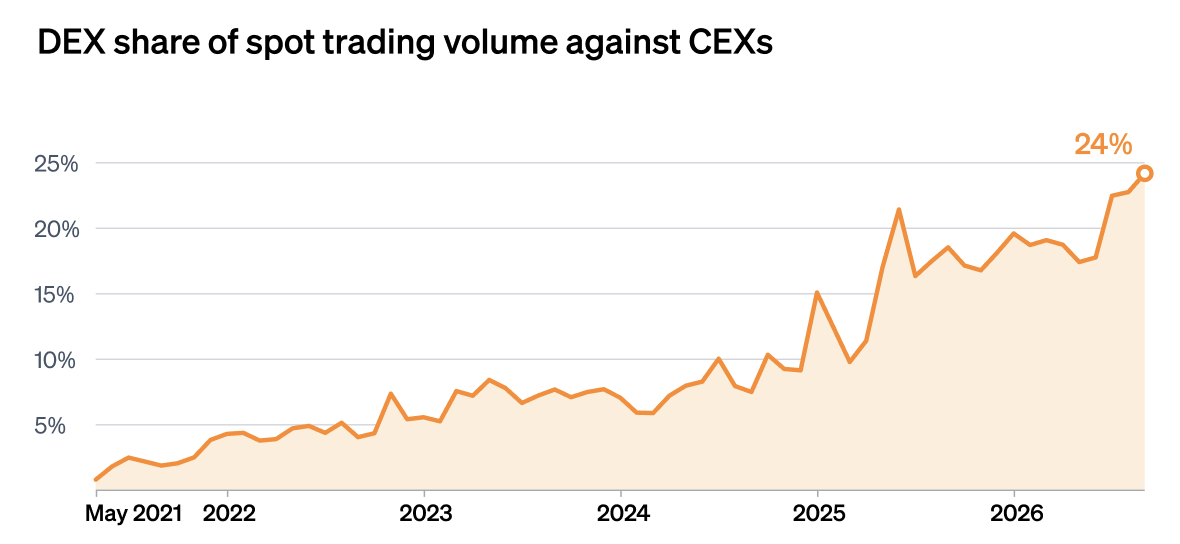
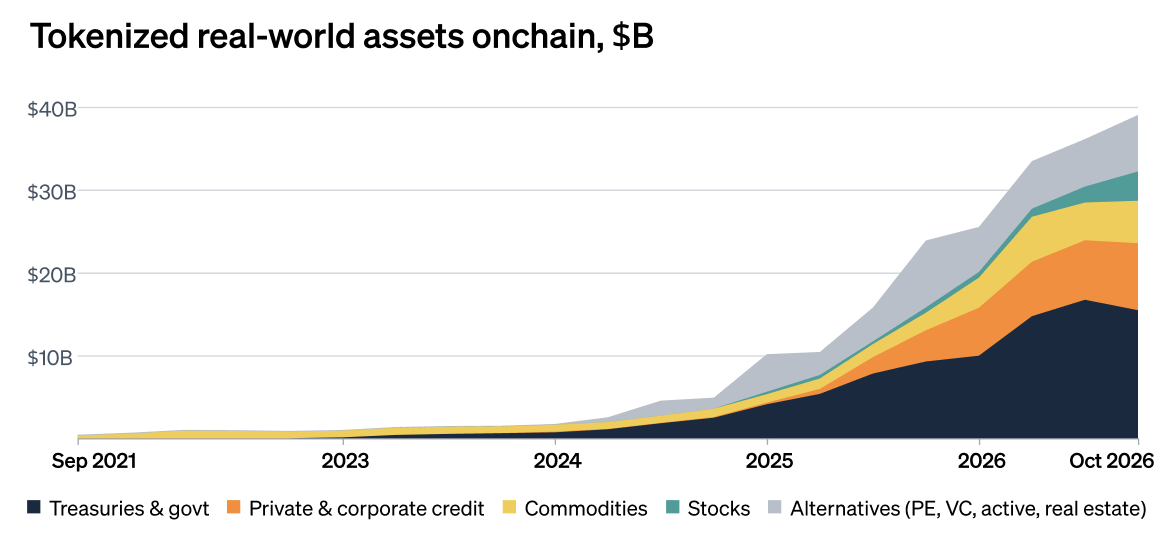
The argument points to two adoption markers rather than to a single token narrative. DEX spot volume as a share of CEX volume was described as being at a historical high and still rising, recently reaching 24 percent, with The Block and DefiLlama cited as sources. Separately, tokenized real-world assets — U.S. Treasuries, private credit, and equities — were described as seeing real use, with growth no longer limited to crypto-native users. Traditional firms, fintech companies, institutional managers, and brokers were said to be building on-chain products and bringing existing customers with them, with rwa.xyz cited for the scale and mix of tokenized RWAs. The open question in the essay is who prices that activity once software and data-analysis costs fall. Value, Applebaum argues, accrues to whoever controls inputs software cannot create.
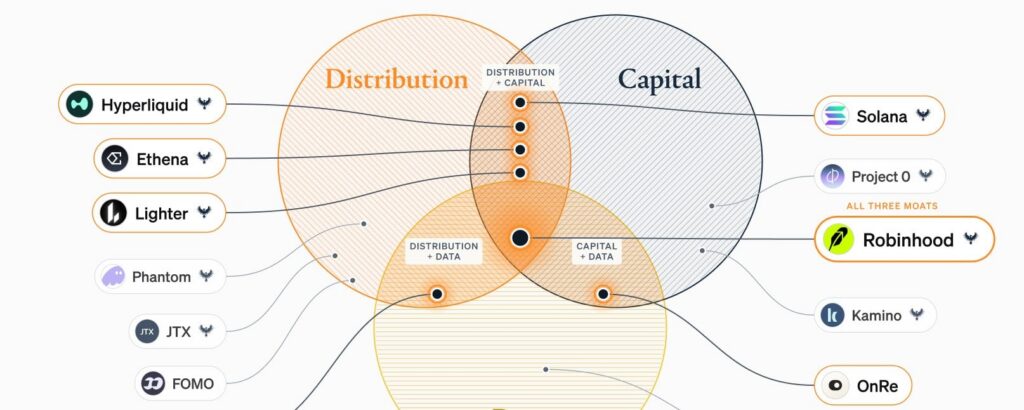
He names three moats — distribution, capital, and proprietary data — and a fourth factor, risk tolerance, that works differently: a wedge into markets rather than a finished barrier. The framework is presented as a successor to earlier Multicoin lines of thought: work tokens and burn-and-mint equilibrium, then “unforkable state” such as liquidity and network effects, then the claim that protocols capture the most value when they must manage real risk.
Distribution: who decides where balances and orders go
Applebaum defines distribution simply as control over where order flow or balances are sent. Not every form is equally sticky. A funded, identity-checked account that is painful to leave can be a real barrier. A thin frontend is easier to contest.
He contrasts this with Joel Monegro’s 2016 “Fat Protocols” essay, which expected blockchains to reverse the internet pattern and concentrate value in base protocols rather than applications such as Google, Facebook, or Amazon. The evidence, in Applebaum’s reading, has pointed the other way, and falling deployment costs are speeding that reversal. The party that owns the customer relationship can route users and balances toward whichever underlying venue pays the highest rebate. Sometimes that party is a standalone app. Sometimes, as with Hyperliquid, it is both a chain and an application.
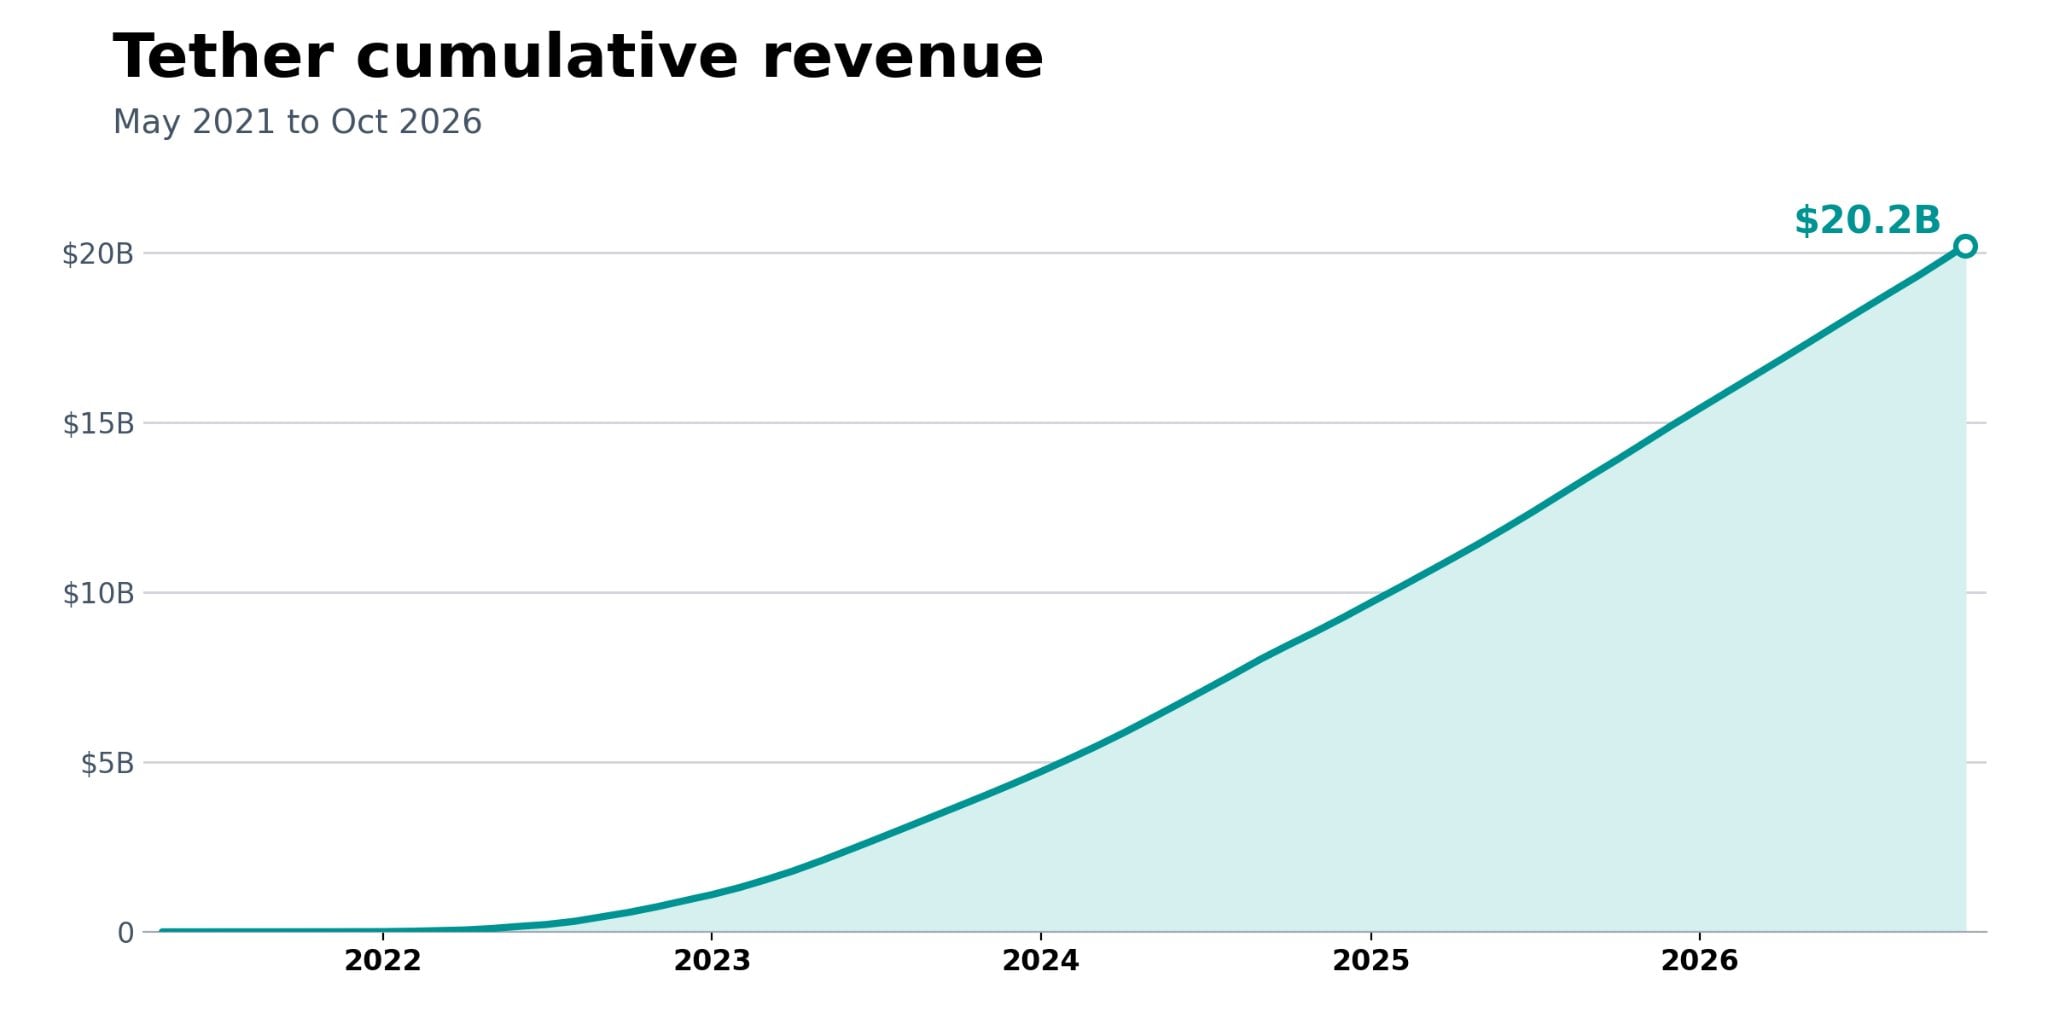
The clearest pricing-power example in the essay is the stablecoin stack. When scale is real and rates are not near zero, issuance has been a strong business: Tether and Circle hold dollar reserves and earn interest, and in most periods share little of it with holders. From 2021 through the period covered by the essay, Tether alone was said to have earned more than $20 billion of near-100-percent-margin interest income. A DefiLlama-sourced chart in the original piece shows cumulative revenue from May 2021 through October 2026 totaling $20.2 billion.
Hyperliquid, by contrast, was described as holding more than $6 billion of USDC as derivatives margin. Those balances generate reserve interest for Circle and its distribution partners. Applebaum’s point is that Hyperliquid came to see itself as the reason the balances exist, and therefore as holding the bargaining chip: if Circle would not share, the venue could substitute a stablecoin willing to share, or in principle issue its own. Earlier in 2026, under an aligned-quote-asset arrangement with Coinbase, about 90 percent of the USDC reserve yield on Hyperliquid was said to flow not to Circle or Coinbase but to the protocol’s Assistance Fund, where it is used to repurchase HYPE. On the $5.5 billion of USDC representing that 90 percent share in the vault, the arrangement was described as an annual revenue source of about $185 million. Hyperliquid does not, in this account, have to run mint-and-redeem pipes, treasury management, or the licenses. Distribution alone was enough to demand a larger share of the economics.
The other side of the same waterfall is wallets and frontends. Early non-custodial wallets struggled to monetize, then treated trading as the high-margin product. At the time of the essay, MetaMask was charging as much as 0.875 percent on swaps, while Uniswap’s average fee over the prior 12 months was 0.13 percent, with most of that going to liquidity providers rather than to the protocol. The venue still has to attract LPs, run infrastructure, and compete on slippage. The wallet mainly has to keep the customer, and can send the order elsewhere if the quote is poor. With enough flow, Applebaum suggests, frontends can internalize more of the matching and keep a larger cut.
A similar split appears in perps. Phantom was said to let users trade Hyperliquid perpetuals while adding 5 basis points on top of Hyperliquid’s native 4.5 basis points. Hyperliquid carries the risk engine, the matching, and the liquidity; Phantom’s higher share comes from the interface and the user relationship. The essay also marks a limit. In the Hyperliquid Builders ecosystem, which it calls a new crowded market, teams were already cutting fees to retain users. Frontends are not immune to commoditization. Crypto wallets are especially exposed because switching costs are low: import a seed phrase and the same assets appear in a new interface within minutes. Leaving a bank or a fintech app is slower — new account, KYC, traditional rails, payroll links, and connected services.
Robinhood is the large-scale version of the same logic. The essay cites 28 million funded accounts. Uniswap was still the main DEX on Robinhood Chain, and Robinhood was described as content with that. Nothing in the cost of software, Applebaum argues, stops Robinhood from shipping its own DEX and pointing flow at it; reach plus AI coding tools could stand up one of the larger layer-2 DEXes quickly. He does not claim Robinhood will do so. Sitting as the liquidity venue has not been its core aim, though the essay notes that a large share of prediction-market orders was already being routed to Robinhood’s own venue, Rothera, rather than to Kalshi. The claim is narrower: writing the protocol is no longer the scarce step. Users, capital, and proprietary data are.
The resulting picture is a waterfall. Frontends such as Phantom take a larger share from venues such as Hyperliquid; venues take yield back from issuers such as Circle. At each layer, the party with distribution has pricing power over the infrastructure beneath it. How much profit sticks depends on how hard it is for the user to leave. Hyperliquid was described as taking about 90 percent of the relevant reserve yield, while frontends running on top of it were already being pushed toward add-on fees of only a few basis points.
Capital: money the model cannot mint
A headless protocol or a backend can look structurally weak next to a frontend. Applebaum’s second moat is capital, which he calls the lifeblood of markets. Traders need it for leverage, market makers need it to quote, and lending protocols need deposits before they can lend. AI can draft code and automate workflows. It cannot create the funds. When a system fails — the essay cites Aave’s KelpDAO episode and MakerDAO’s Black Thursday — someone has to absorb the loss.
Liquidity itself is treated as real but leaky. It has logarithmic network effects: traders go where liquidity is, and liquidity follows traders. Open interest on a venue such as Hyperliquid is an advantage, but the money belongs to users who can withdraw it. The essay recalls repeated DeFi episodes in which incentives and vampire attacks moved liquidity, and in which much of it left once the incentives ended. Two narrower forms of capital are presented as more durable.
The first is a DeFi prime broker. In traditional markets, prime brokers supply leverage and financing and let hedge funds reuse one pool of capital across venues and strategies instead of posting full margin everywhere. The essay puts industry prime-brokerage revenue at about $15 billion in 2020 and about $27 billion in 2024, tied to hedge-fund growth and to multi-strategy “pod shop” expansion. The DeFi version, it argues, could be larger because smart contracts automate work that makes small clients uneconomic for a traditional prime broker. The same shared-margin logic could serve a $500 trade and a pod managing hundreds of millions. Today a trader often posts separate margin on Hyperliquid, Aave, Lighter, Morpho, Variational, and Kamino. That inefficiency worsens if the book also includes tokenized equities, Treasuries, or private credit. A long tokenized stock in one venue and a short index perpetual in another should not, where the risks offset, require full margin on both sides. The software for that netting is getting easier to write. The hard parts are a balance sheet large enough to finance the positions, a low cost of funds, and the operating experience to avoid getting run through in a liquidation. Cheaper capital can mean better terms, more clients, and still cheaper capital — a scale loop the essay treats as strong.
The second form is capital that backstops protocol risk. This continues an earlier Multicoin argument that tokens which do not manage risk are easier to fork than tokens that do. Hyperliquid’s HLP vault makes markets and takes on liquidated positions; depositors share profits and losses. In March 2025 the vault was said to have lost about $4 million handling a large ETH liquidation, and a later JELLYJELLY episode again stressed the book. Both are used to illustrate why a derivatives-DEX insurance fund matters. Aave’s Umbrella is cited as a related design: users take bad-debt risk in exchange for extra yield. The contracts can be forked. The money inside them cannot. The caveat is that this is still other people’s capital. If yields are higher elsewhere, depositors can leave. Some stickiness may come from overlap between token holders and vault depositors — for example, HYPE holders keeping dollars in HLP because the vault’s solvency protects the exchange and therefore their token exposure. The most stable version, in the essay, is a balance sheet built from retained earnings, which does not exit for a short-lived yield or points program.
Binance is the owned-balance-sheet example. After a $6.3 billion theft on October 29, the exchange was said to have filled the hole with SAFU reserves and, mainly, company funds, restored withdrawals within days, and seen net assets leave by only 3 percent. The essay treats market trust in that balance sheet as what contained a run, while noting that the episode was still early. As activity moves into private credit, tokenized equities, and other RWAs, demand for insurance capital and risk capital is expected to rise. Protocols that actually supply and run that capital, rather than only ship software, are expected to capture more of the value.
Proprietary data: public books versus underwriting books
The third moat is information, with an explicit limit. DeFi grew up on the idea that financial data should be public, which works for overcollateralized crypto lending and for spot markets. As more RWAs move on-chain, Applebaum expects more businesses built on information that is not public. The defensible combination is proprietary non-public data plus the ability to price and underwrite from it.
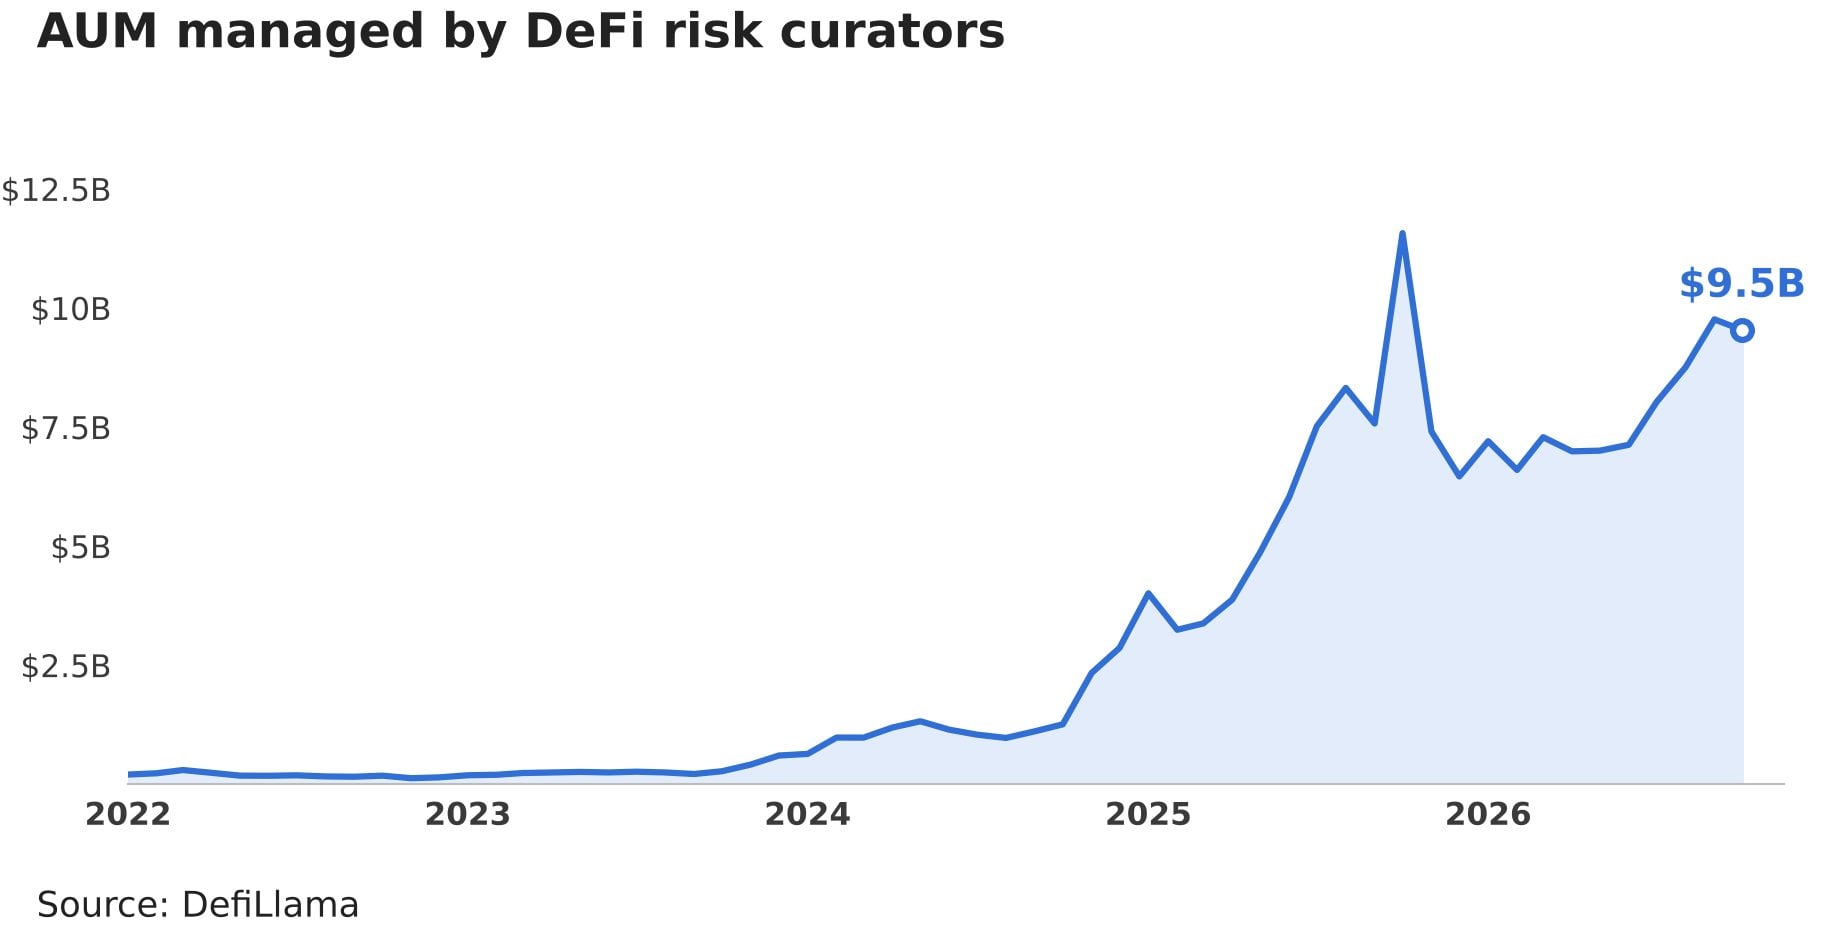
Lending already shows the public-data version. On Morpho, Kamino, Euler, and similar venues, risk curators were said to be assessing risk on $9.5 billion of depositor capital, with DefiLlama cited for that assets-under-management figure. Curators receive limited permissions inside vault contracts: which markets to allocate to, which risk parameters to set, and how to watch collateral. Despite that $9.5 billion, their revenue was described as very small relative to traditional managers with more discretion and more responsibility. Many charge almost nothing. Steakhouse Financial, the largest curator by assets, was cited at a blended take rate of 22 basis points; the curator average was 19 basis points. Part of the explanation offered is that risk-adjusted DeFi yields were not especially attractive, possibly because a large amount of idle capital sat in Aave. Part of it is structural: Morpho and Kamino had commoditized the vault layer and sit between curator and depositor, which is the distribution point again. The deeper claim is that most curators are reading the same public data. For ETH- or BTC-backed loans, price, liquidation rules, and collateral are visible to everyone. AI makes copying a risk model easy, so differentiation collapses toward one-off judgment and a track record, which the essay expects to compress fees over time.
OnRe is the contrast. It is described as an on-chain reinsurer that raises capital from investors and uses it to underwrite real-world insurance risk. That requires claims history, loss probabilities, the actual policy language, and actuaries who can read those materials. None of it is on a block explorer. A model without the internal reinsurance book cannot produce the price. OnRe was said to charge a 75-basis-point management fee plus 20 percent of excess returns. At then-current returns, that implied an annualized fee rate of about 3 percent, roughly 16 times the average DeFi curator. Applebaum notes that these are different businesses with different risks, and that part of the premium compensates for illiquidity and principal loss. The comparison is still used to support the narrower claim: proprietary data, underwriting skill, and a client relationship can support a much higher price; the same public data and the same tools as everyone else tend toward a commodity outcome.
Where the essay thinks value does and does not stick
Applied to base layers, the reading is cool. L1 and L2 tokens are described as being in a harder position because chains used to confer two of the moats — distribution and capital — on the applications built on them, and that dividend is fading.
Distribution once came from users parking assets on the busiest chain. Building on Ethereum reached Ethereum users; building on Solana reached Solana users. For early Uniswap, Compound, Aave, Kamino, or MakerDAO, starting where users already were mattered. Interoperability weakens that bind. A user of an app such as fomo can open an account on a phone and trade assets across chains without managing the underlying chain. More new users, the essay expects, will arrive through Revolut, Nubank, and Robinhood, which already have tens of millions of customers and do not ask those customers to hold their own keys.
Capital once arrived as an ecosystem wealth effect: appreciation in SOL or ETH left users with more funds on that chain, and bridging friction plus community loyalty kept it there. Bridging is smoother now. New money arrives as stablecoins, tokenized assets, and institutional flows, and RWA issuers including Securitize, Superstate, and Ondo are described as preferring to deploy on every major chain. On data, general-purpose chains barely had a moat to begin with, because most on-chain financial information was public. AI also erodes a different historical advantage: the developer stack. Ethereum’s lead over newer chains such as Solana or Aptos included mature tooling, audited code, and a dense integration ecosystem. If models can port and refactor applications across virtual machines, that lead matters less. What remains is competition on execution and settlement. With plentiful blockspace, the essay expects fees per transaction to keep falling.
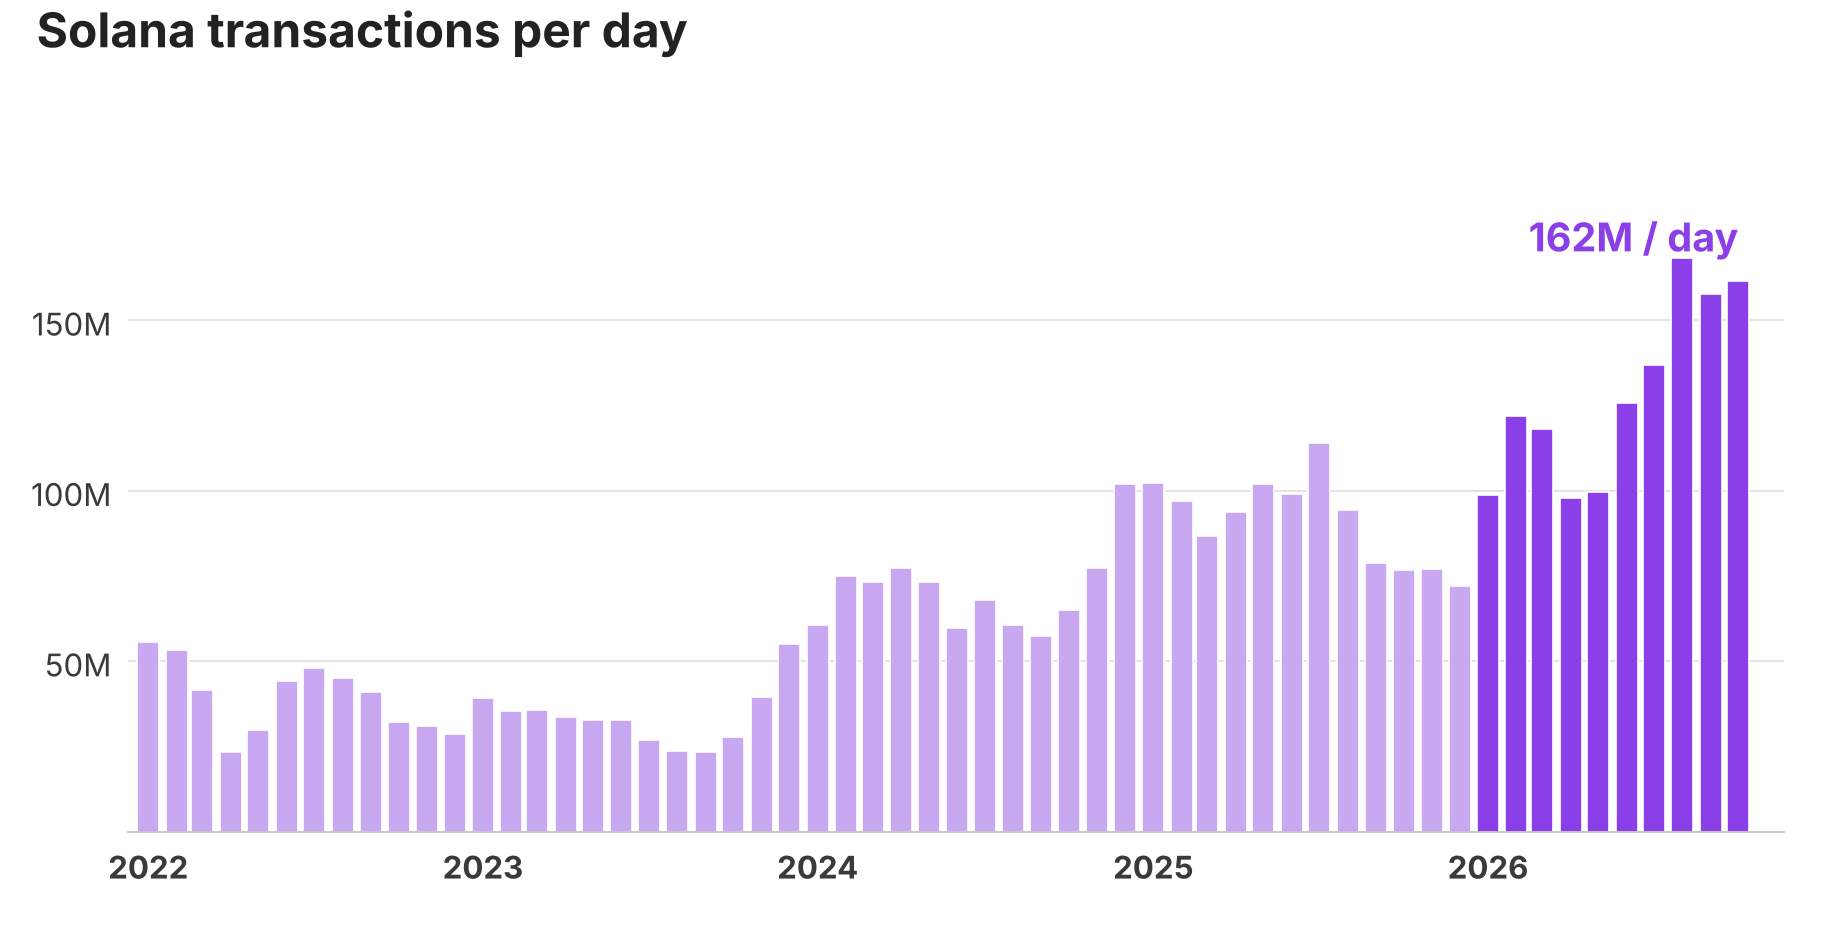
That is not a claim that chains cannot be valuable. Applebaum cites an earlier summit argument from Tushar that an L1 token can be, at once, a capital asset, a commodity asset, and a store of value. Even at one cent per transaction, a Solana that eventually processed one billion payments a day would still produce $3.65 billion in annual fees. The essay’s own datapoint is smaller and already observed: Solana daily transactions reached 162 million in 2026, with Blockworks Research cited. The implication he draws is that the reason a chain is valuable later may not match the reason investors first bought it.
At the application and protocol layer, the winners in this framework hold at least one of the three moats: a direct customer relationship that is hard to leave, as with Robinhood or Hyperliquid; a balance sheet that can absorb losses; or underwriting ability others cannot reach. Model quality does not, in the essay, make those three as copyable as software. Whether the wrapper is equity or a protocol token is treated as secondary. Both can participate. Recent SEC guidance and draft rules are described as sketching a compliant path for tokens to capture value, and Multicoin says it intends to keep allocating to that path. The test Applebaum wants is whether the enterprise, whatever the wrapper, controls a scarce input, has pricing power because of it, and can turn that into returns for its investors. As more finance moves on-chain, he expects the valuation and earnings gap to widen between protocols that hold a real moat and protocols that are mainly code. The firm, describing itself as one of the largest investors in the category, says it is spending substantial effort sorting which projects actually hold and can defend these barriers.
Risk tolerance as a temporary wedge, not a moat
The incumbent reading is acknowledged directly. Robinhood has the customers. Goldman Sachs is presumed to have a larger balance sheet than any DeFi prime broker. Moody’s has data and licenses. If software is nearly free and moats are expensive, the firms that already own the moats look favored.
Startups, in the essay, keep one advantage: they will take risks incumbents will not. AI cuts both ways. It lets Robinhood assemble a DEX over a weekend, and it lets a three-person team move at a similar build speed. The opportunity Applebaum highlights is therefore not “build the same product cheaper.” It is entry into markets and customers that large firms leave alone because of regulation, operations, reputation, or because the niche first looks too small. Several cases are offered as already visible, not as a forecast basket.
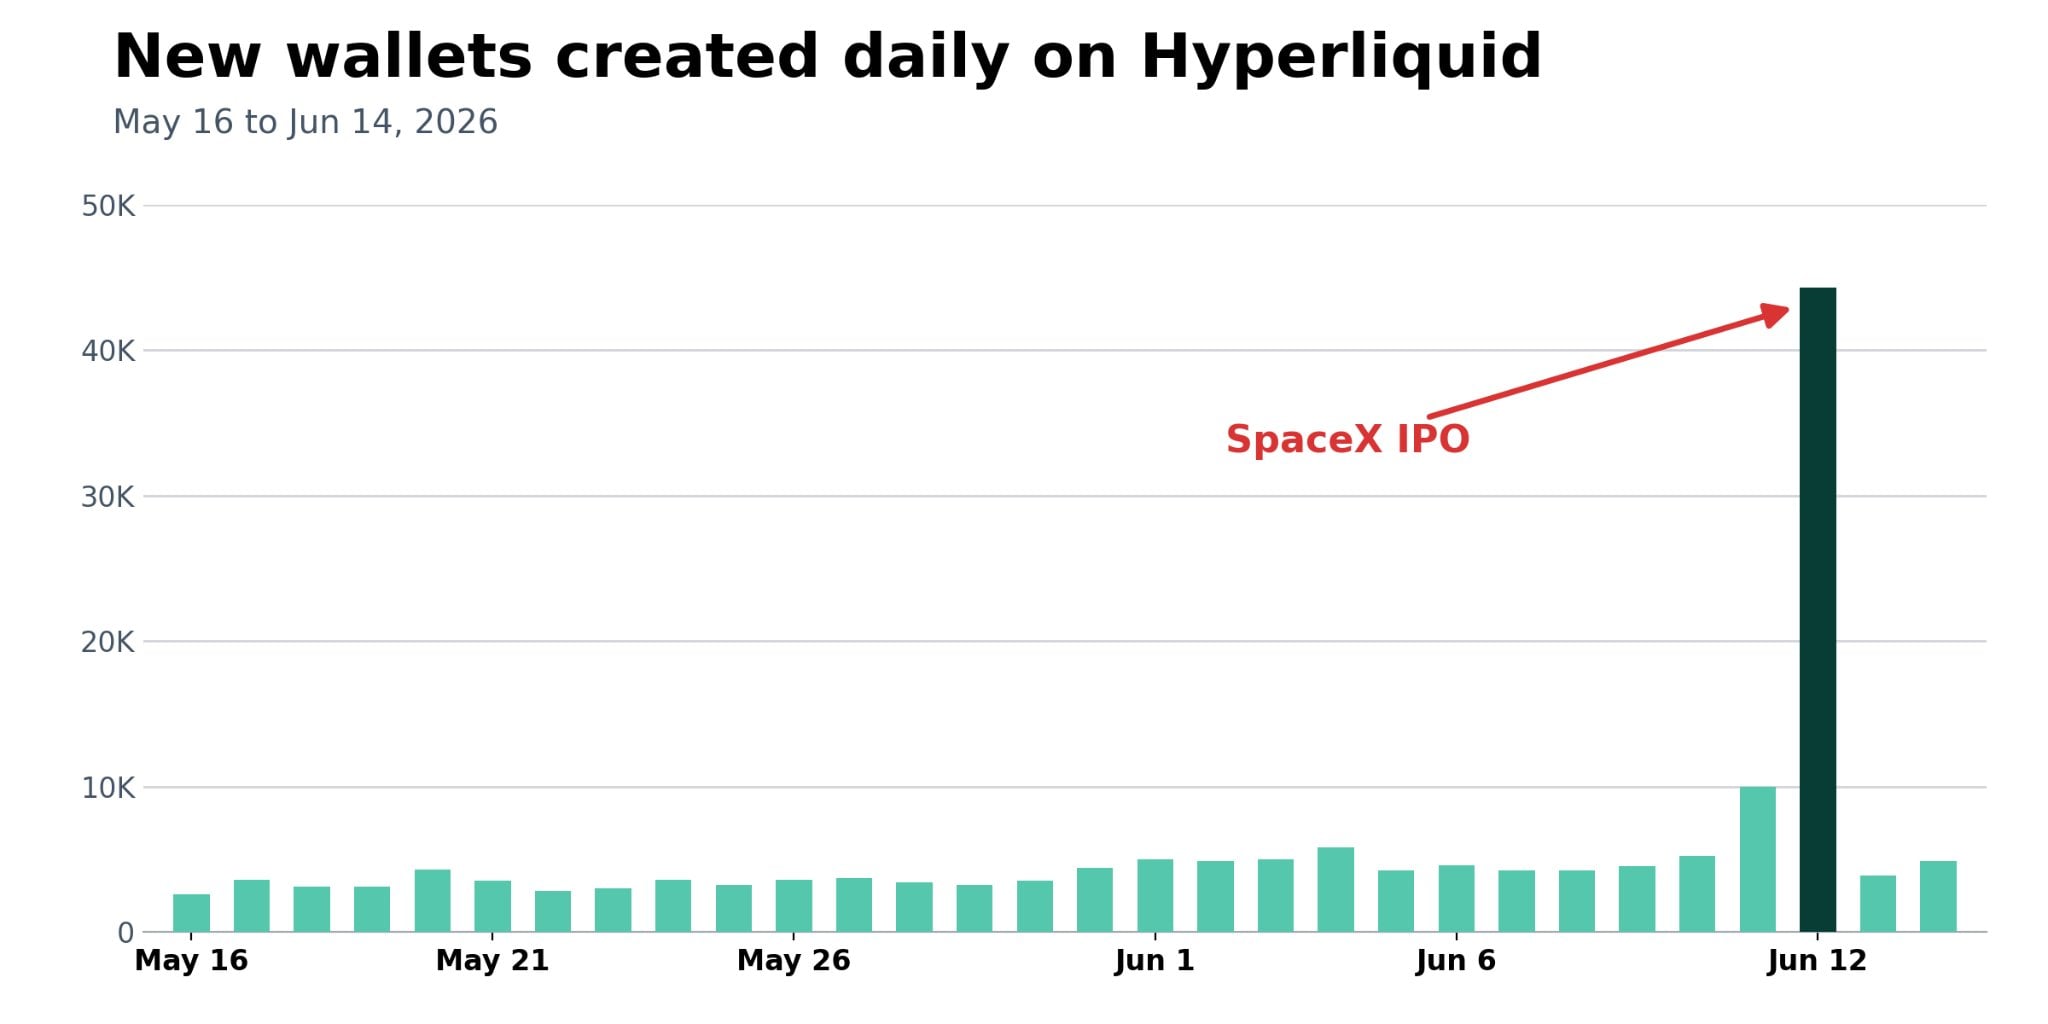
Ethena built a synthetic dollar around delta-neutral hedging. Basis trades are familiar on Wall Street, but traditional firms were unwilling or unable, for compliance or internal reasons, to run that trade on crypto venues. Ethena was cited at $5.4 billion in assets under management. Pump.fun and fomo started near zero, built trading experiences around memecoins as a new asset category, and captured distribution, becoming two of the more visible winners of the cycle in the essay’s account. Hyperliquid entered a derivatives market dominated by Binance, Bybit, and OKX and took share, including pre-IPO perpetuals on unlisted companies such as OpenAI and Anthropic — listings a licensed traditional exchange would not offer. Those markets were said to pull in new traders and new liquidity. HyperTracker figures in the original piece show daily new Hyperliquid wallets from May 16 to June 14, 2026, with new wallets exceeding 40,000 on the day of the SpaceX IPO.
On capital, Project 0 is described as financing DeFi collateral that traditional prime brokers will not touch. On data, USD.ai is described as underwriting loans against GPU hardware, an asset traditional banks have little experience pricing. The shared pattern is an empty patch left by regulatory constraint, operational complexity, reputational risk, or small initial size. Applebaum expects more such patches. AI lowers the cost of making the financial product; DeFi lets a small team reach customers and move capital without rebuilding a full traditional stack. Risk appetite by itself is not a lasting moat. Regulation catches up, and once a market is proven, incumbents enter — the spot Bitcoin ETF market is the example given. A startup does not need all three moats on day one. It needs a gap the incumbent will not enter, and enough time to convert that gap into distribution, owned capital, or proprietary underwriting. After that, the essay’s language is compounding rather than a permanent outsider advantage.
What the argument does and does not claim
The close of the piece restates the decade-scale view: trillions of dollars of financial activity moving on-chain, and AI pushing the cost of the software that serves it to a level not seen before. Direct customer relationships, real risk capital, and non-public data do not cheapen with the code. Holders of those inputs keep pricing power. That is the basis for Applebaum’s constructive view of a newer set of DeFi startups — not a claim that every new protocol token participates, and not a ranking of sectors. Code can be forked or generated. None of the three moats can. The excess-return opportunity he points investors toward is the ability to tell which teams actually control one of them. A disclosure note in the original directs readers to the Multicoin site for the firm’s own statement.
The essay is an investor’s framework, not a measurement of how much of the described waterfall has already been locked in. Several of its sharpest numbers — the 90 percent yield split, curator take rates, the OnRe fee comparison, the Binance outflow figure — are presented as illustrations of bargaining power and stickiness, not as a completed industry structure. Frontend fee compression inside the Hyperliquid Builders market is already offered as evidence that distribution itself can be competed away when users can leave easily. The narrative people are being asked to adopt is that AI commoditizes the build and leaves three older financial scarcities in place. The evidence underneath it is a set of specific venue, wallet, curator, and RWA examples, each still dependent on whether users, depositors, and data access remain where the essay says they are.
Original article: TechFlow, compiling Spencer Applebaum’s Multicoin essay, November 11, 2026.