On November 11, 2026, ChainCatcher published an essay by Spencer Applebaum, general partner and co-head of venture at Multicoin Capital, compiled by 谷昱 (Gu Yu). It is an investor framework, not a neutral market tally. The claim is that AI is collapsing the cost of building DeFi software, while the scarce inputs of a financial business — customers, capital, and proprietary data — stay about as hard to obtain as before.
The story the essay is telling
Applebaum opens with a before-and-after. Five years earlier, he writes, building a DEX or a lending protocol meant raising $3 million, hiring five engineers, and spending six months on an MVP. By the time of the essay, a founder using Claude Code could assemble most of that over a weekend. Ask a frontier model for a perpetual-futures exchange, he says, and the output can include a matching engine, a risk engine, a trading interface, an API, and much of the rest of the stack.
His distinction is between software and a financial franchise. AI, in this account, makes competition easier across nearly every part of the software industry, but financial services remain among the hardest businesses to commoditize, because the valuable parts have little to do with the code. A loyal customer base, a large balance sheet, and proprietary data plus underwriting skill take years of relationships, a track record, and trust. A model can write a lending protocol in an afternoon. It cannot, he argues, conjure $10 billion of stablecoin deposits into a contract, or sign up 28 million customers for a new neobrokerage.
From that gap, Multicoin draws an explicitly bullish conclusion about DeFi: over the decade that followed the essay, trillions of dollars of financial activity would move onchain, products serving that activity would get much cheaper to build, and the features that make a financial business valuable and defensible would not get easier to copy. That is the firm’s thesis. It is not a measured adoption series, and it does not make every DeFi token the same kind of claim.
How Multicoin says its own framework changed
Applebaum presents the essay as the next pass through a value-capture argument the firm had already revised as the market grew.
- Early on, Multicoin looked at how application tokens might capture value through designs such as work tokens and burn-and-mint equilibrium (BME).
- Later, the emphasis moved to defensibility and unforkable state: anyone can fork open-source code, but not liquidity or network effects.
- More recently, the firm argued that DeFi protocols capture the most value when some risk has to be managed.
He says each of those claims has, in some measure, been borne out. The November 2026 essay adds a sharper line: once software and data analysis are cheap, value flows to whoever controls inputs that software cannot create.
The backdrop he cites, and what it does not settle
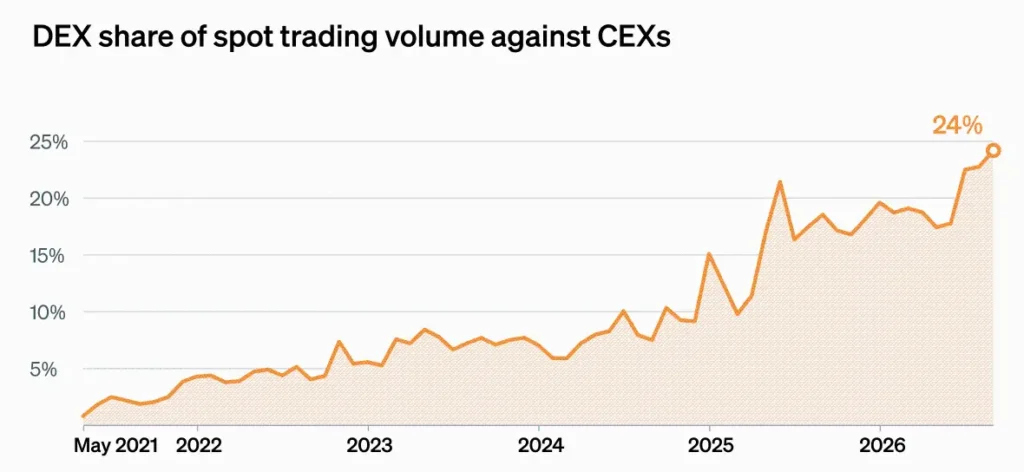
Before the moats, the essay states a belief. DeFi, Applebaum writes, will keep taking share from centralized crypto finance and eventually from traditional finance as a whole. On the first step, he points to DEX share versus CEX share at historical highs and still climbing, citing The Block and DefiLlama. The ChainCatcher text does not give a specific percentage.
He also says tokenized assets — Treasuries, private credit, and equities — are seeing real adoption, and that the growth is not only crypto-native. Existing institutions, fintechs, institutional asset managers, and traditional brokerages are building onchain and bringing customers with them. The cited source is rwa.xyz. The prose does not extract a single adoption total from that reference.
The pivot is that today’s blue-chip DeFi protocols are not automatically the ones that capture that growth. Cheaper software and cheaper analysis, in his view, push value toward control of scarce inputs.
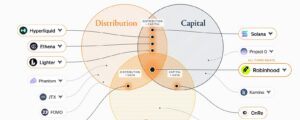
He names three principal moats: distribution, capital, and proprietary data. A fourth factor, willingness to bear risk, is treated differently — as a wedge, not a durable moat — and held until the end.
Moat 1: distribution, meaning control of where flow goes
Applebaum defines distribution narrowly: control over where order flow or balances are sent. Not all of it is equally sticky. Funded accounts that are hard to move are a real barrier. An interface alone is more exposed to competition.
He sets this against Joel Monegro’s 2016 Fat Protocols essay. That argument held that, unlike the internet — where large value accrued in applications such as Google, Facebook, and Amazon — blockchains would invert the stack and send most value to the base protocol. Applebaum says the evidence has pointed the other way, and that the trend is accelerating. As protocols get cheaper to launch, value moves toward whoever owns the customer relationship and can route users and balances to the highest bidder. Sometimes that owner is an application. Sometimes, as with Hyperliquid, it is a chain that is also an application.
Stablecoin issuance versus the venue that holds the balances
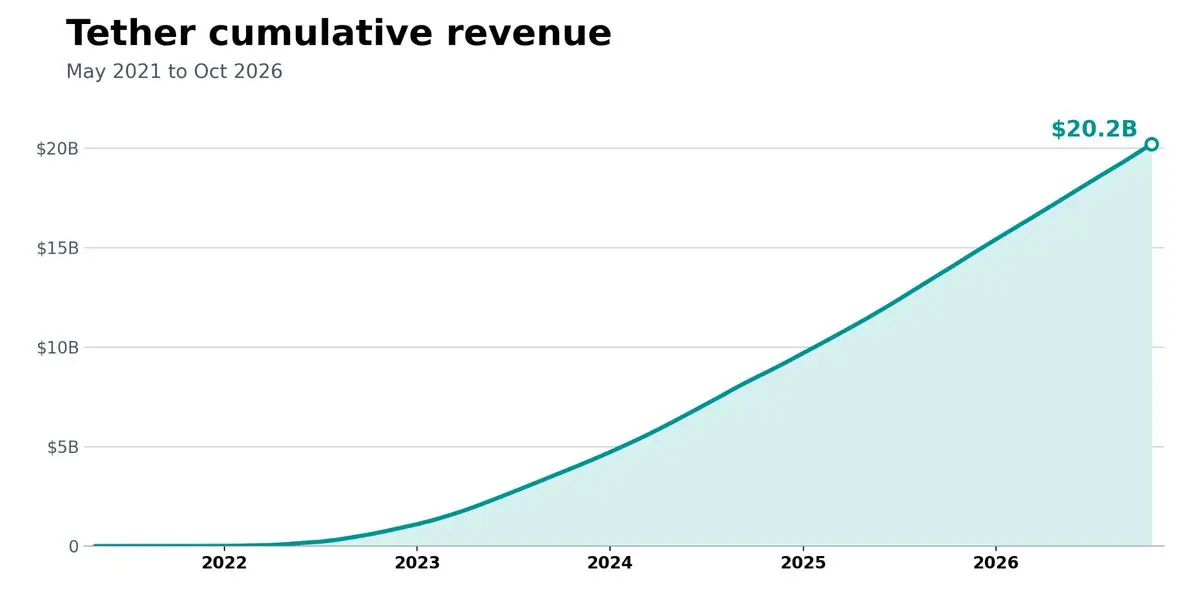
Issuance, he writes, has historically been an excellent business if the issuer reaches scale and rates are not near zero. Tether and Circle hold dollar reserves, earn interest, and in most cases pay holders nothing. Citing DefiLlama, he says Tether alone has earned more than $20 billion in interest income this way since 2021, at margins near 100%.
Hyperliquid is his example of distribution pushing back. The platform, he writes, had more than $6 billion of USDC posted as derivatives collateral. Those balances generate substantial reserve revenue for Circle and its distribution partners. Hyperliquid, in this telling, concluded that the balances existed because of Hyperliquid, and therefore that it had leverage: if Circle would not share the economics, Hyperliquid could replace USDC with a stablecoin that would, or in principle issue its own.
Earlier in 2026, according to the essay, Hyperliquid reached a deal with Coinbase under its Aligned Quote Asset (AQA) framework. Under that deal, roughly 90% of the USDC reserve yield on Hyperliquid flows to the protocol’s Assistance Fund, which uses it to buy HYPE, rather than to Circle or Coinbase. Applebaum says the vault holds $5.5 billion of USDC, which he describes as the 90% directed toward HYPE, and that this is about a $185 million revenue line for Hyperliquid as of the essay.
The point he stresses is what Hyperliquid does not run: minting and redemption, vault management, or the regulatory licenses. It owns distribution, and in his account that is enough to demand more of the economics.
Wallets and front ends take a cut — until they compete with each other
The other side of the claim is wallets and front ends. Non-custodial wallets, he writes, struggled for a long time to monetize. They eventually made trading — which he calls the most profitable business in crypto — a first-class product.
On those trades, MetaMask charges 0.875%. Uniswap’s average trading fee over the prior 12 months was 0.13%, and most of that value, he says, goes to liquidity providers rather than to the Uniswap protocol. His summary is that the wallet earns far more than the venue executing the trade. The venue has to attract LPs, maintain complex infrastructure, and compete on execution. MetaMask has to win and keep the customer. If a DEX does not offer a good price, the wallet can route elsewhere. With enough order flow, he adds, it can internalize a large share and keep more of the economics.
He sees the same pattern in perpetuals. Phantom lets users trade perps on Hyperliquid and charges an additional 5 basis points on top of Hyperliquid’s 4.5 basis point fee. Hyperliquid runs the risk engine, matching, and liquidity. Phantom, he argues, earns more simply by owning the interface and the user.
He also marks a limit. Among Hyperliquid builders, the essay describes a new red ocean already in a price war, with teams cutting fees to improve retention. Even the front-end layer is not immune to commoditization. More broadly, he calls crypto wallets somewhat fragile because switching costs are very low: a user can connect a private key or seed phrase to another wallet and reach the same funds within minutes. Leaving a bank or a fintech is heavier — a new account, KYC, a transfer over traditional rails, payroll reconnected, and other linked services possibly updated.
Fintech distribution, including a Robinhood case he does not treat as a prediction
For funded distribution, he uses Robinhood’s 28 million funded accounts. Uniswap, he writes, is the primary DEX on Robinhood Chain, and Robinhood has not objected. His point is capability, not a forecast. As AI lowers the cost of financial software, nothing in the stack stops Robinhood from building its own DEX and sending users there. With that reach and then-current coding tools, he says, it could stand up one of the largest layer-2 DEXes in DeFi almost overnight.
He pulls that back explicitly. Multicoin is not saying Robinhood will do this. Owning liquidity has not historically been Robinhood’s primary goal, though the essay notes that Robinhood had started routing substantial flow to its own prediction market, Rothera, rather than to Kalshi. Building the protocol, in this framing, is no longer the hard part. Attracting users, capital, and proprietary data is.
He then describes a waterfall. Front ends such as Phantom capture more of the economics from trading venues, and venues such as Hyperliquid capture more from stablecoin issuers such as Circle. In each case, the business with distribution has pricing power over the infrastructure below. How much a layer keeps depends on how easily users leave. Hyperliquid, in his account, took roughly 90% of the reserve yield, while front ends on Hyperliquid had already compressed fee competition into the low single-digit basis points.
Moat 2: capital that can take a loss, not just liquidity that can leave
Applebaum grants the inference from the distribution section: headless protocols and back-end infrastructure are at a disadvantage in some cases. Capital is the next moat.
Traders need it for leverage, market makers need it to keep quoting, and lending protocols need deposits in order to lend. AI can write code and automate workflows. It cannot create the money those systems depend on. When something breaks — he cites Aave’s KelpDAO incident and MakerDAO’s Black Thursday — someone has to bear the loss.
He separates that from liquidity. Liquidity, he writes, has a log(n) network effect: traders go where liquidity is, and liquidity follows them. Hyperliquid’s open interest is a real advantage, but that capital belongs to users who can move it. DeFi has already seen liquidity shift from one protocol to another, often on token incentives and vampire attacks, and often leave when the incentives dry up.
Two forms of capital, in his view, can support longer-term defensibility.
A DeFi prime broker
Prime brokers in traditional markets provide leverage, finance trades, and let hedge funds use one pool of capital across markets and strategies instead of posting collateral at every venue. He calls the business large. Industry-wide prime-brokerage revenue rose from about $15 billion in 2020 to about $27 billion in 2024, with growth in hedge funds and in multi-manager pod shops that rely heavily on financing.
He thinks the onchain opportunity may be larger. Traditional prime brokers mainly serve large institutions, because smaller clients are operationally expensive. Smart contracts, he argues, could automate much of that work and offer it to anyone from a person trading $500 to a pod at Millennium managing hundreds of millions of dollars.
The inefficiency he describes is specific. A trader typically has to post collateral separately on Hyperliquid, Aave, Lighter, Morpho, Variational, and Kamino. As tokenized equities, Treasuries, private credit, and other real-world assets move onchain, that problem gets worse. A fund long tokenized equities in one venue and short an equity-index perpetual in another should not, he argues, have to fully collateralize both positions when some of the risk offsets.
Building the software to manage that is getting easier, he says. The hard part is the balance sheet that finances the positions, a lower cost of capital, and the risk-management skill to avoid liquidation. Over time, a prime broker with cheaper capital can offer better terms, attract more clients, and use that scale to finance itself more cheaply. He expects the business to show strong returns to scale. That is an argument about structure, not a claim that a named protocol already holds the role.
Backstopping protocol risk
The second use of capital is standing behind a protocol’s risk. It connects to an earlier Multicoin argument that tokens tied to protocols which do not manage risk are easier to fork out than tokens tied to protocols which do.
Hyperliquid’s HLP vault is the example. It provides liquidity by making markets and taking over liquidated positions. Depositors share profits and also absorb losses. In March 2025, Applebaum writes, HLP lost about $4 million closing a large ETH position, and the later JELLYJELLY episode exposed it to further risk. He treats both as reasons derivatives-DEX insurance funds matter. Aave’s Umbrella, in the same passage, lets users earn yield in exchange for backstopping bad debt.
Anyone can fork the HLP or Umbrella contracts. They cannot fork the capital in them. The limit he names is that this is third-party capital: if depositors find a better yield, they may leave. The counterargument is overlap. Some HYPE holders might keep dollars in HLP to make the exchange safer and to protect the token position. The more durable version, he says, is the protocol’s own balance sheet, built from retained earnings, which does not leave to chase a newer yield or a points program.
Binance is his recent illustration, and it should be read as his account. He writes that after a hack on October 29 in which Binance lost $6.3 billion, the company covered the loss with SAFU reserves and corporate funds — mainly the latter — reopened withdrawals within days, and saw only a net 3% of assets leave. He calls the reading early, but says the perceived balance sheet helped prevent a bank run.
As DeFi moves into private credit, tokenized equities, and other RWAs, he expects demand for insurance and risk capital to keep growing. Protocols that actually provide and manage capital, in this view, capture far more value than protocols that only deliver software.
Moat 3: proprietary data, which public ledgers do not supply
The third moat is information, with a limit stated up front. DeFi was built on the idea that financial data should be public, and that works well for crypto-collateralized lending and spot trading. As more RWAs come onchain, he expects more businesses built around information that is not public. The moat is that data combined with the ability to underwrite from it.
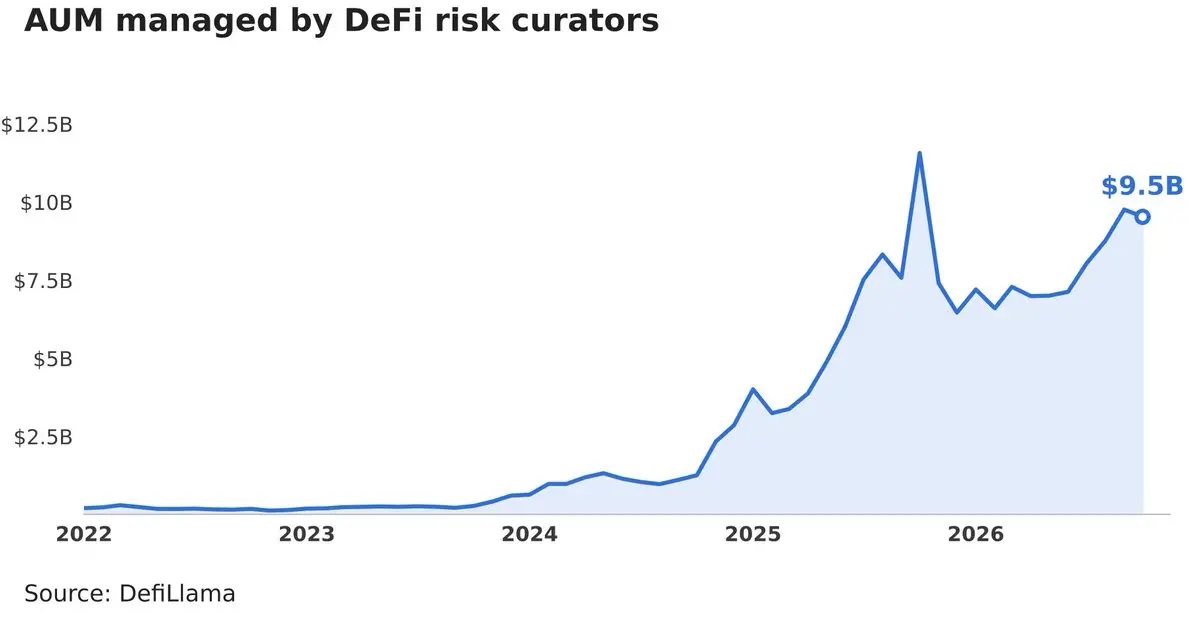
Lending is where he says this appears first, and where it mostly fails to produce a moat. Curators on platforms including Morpho, Kamino, and Euler assess risk for depositor funds, at a combined scale he puts at $9.5 billion. Inside vault contracts they have limited control over which lending markets receive funds, what the risk parameters are, and how collateral positions are monitored. Despite that $9.5 billion, he says revenue is very small compared with traditional asset managers that have more discretion and more responsibility. Many curators charge nothing. Steakhouse Financial, described as the largest DeFi risk curator by AUM, takes 22 basis points. The average curator take rate is 19 basis points.
He gives two partial reasons, then a larger one. Risk-adjusted DeFi yields were unattractive at the time of the essay, likely in part, he says, because of idle capital sitting in Aave. Morpho and Kamino had also made the vault layer more alike and sat between curators and depositors, which returns the argument to distribution. The larger issue is that curators mostly work from the same data. Lending against ETH or BTC uses public prices, public liquidation rules, and public collateral. AI makes the risk model easy to copy, so curators compete on judgment — much of the risk-taking already set by the algorithm — and on track record. Over a long enough span, he expects that to pressure fees.
OnRe is the contrast. Applebaum describes it as an onchain reinsurer that takes capital from investors and uses it to underwrite real-world insurance risk. That requires historical claims data, loss probabilities, and the insurance contracts themselves, plus people who understand the data. None of this is on a block explorer. A frontier model without access to the reinsurance book cannot underwrite it, however capable the model is.
That, he writes, is why OnRe can charge a 75 basis point management fee plus 20% of the yield. At the returns he was using, that is about 3% a year, 16 times the average DeFi risk curator. He notes that these are different businesses with different risks, and that part of the fee premium reflects illiquidity and the possibility of loss. The boundary he wants kept is this: a business with proprietary data, underwriting skill, and relationships can charge much higher fees. The same data and the same tools as everyone else tend, in his view, toward a commodity.
What he thinks that does to chains versus applications
A cynical reading, which he lays out rather than treating as the whole story, is that infrastructure tokens such as L1s and L2s are in a difficult position. Blockchains used to supply two of the three moats to new DeFi applications: distribution and capital.
Historically, users kept assets on the chain where they were most active. Building on Ethereum reached Ethereum users. Building on Solana reached Solana users. For a team starting Uniswap, Compound, Aave, Kamino, or MakerDAO with no existing customers, no assets, and no financial relationships, launching where users already were made the start much easier.
He says better interoperability is weakening that. A user who onboards through the fomo app can trade any asset on any chain without having to think about the chain. More new users, he expects, will enter DeFi through fintechs such as Revolut, Nubank, and Robinhood, which already have tens of millions of customers and do not require a funded wallet as the front door.
Capital through ecosystem wealth effects is the second advantage he thinks is fading. As SOL and ETH prices rose, users had more to deploy into applications on those chains. Capital tended to stay because bridging was painful and users were tribal. Bridging is easier now, he writes, and capital arrives through stablecoins, tokenized assets, and institutions, so a new protocol depends less on any single token’s wealth effect. RWA issuers also want to launch on every chain. He points to Securitize, Superstate, Ondo, and others as already doing so.
On data, there was never much of a chain-level moat. Almost all onchain financial information is public, so chains and applications never had much proprietary data to defend. AI, he adds, also wears down another historical advantage: the developer ecosystem. One of Ethereum’s largest advantages over newer chains such as Solana or Aptos was mature tooling, audited libraries, and integrations. As AI makes it easier to port applications across virtual machines, that advantage matters less.
General-purpose chains, in this account, are losing the distribution and capital edges they used to have, and they did not start with much of a data moat. What remains is competition on execution and settlement, while blockspace is abundant and fees keep falling.
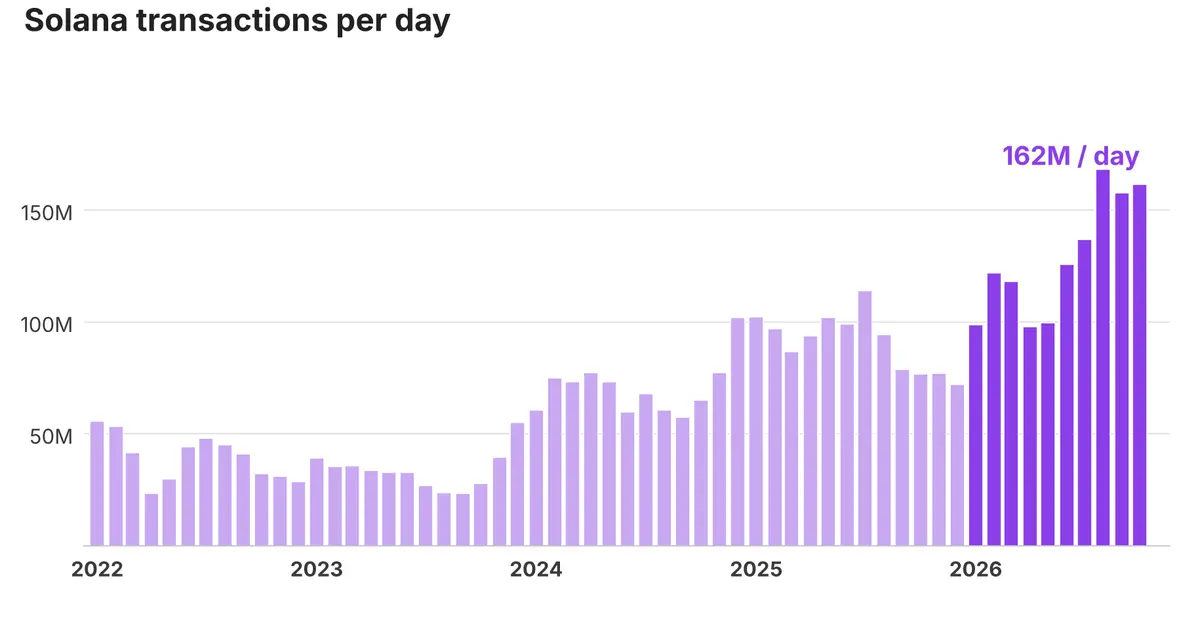
He does not treat that as a claim that chains cannot be valuable. Referring to an argument Tushar made in a summit talk a few years earlier — the essay gives no surname — he says an L1 token can be a capital asset, a commodity asset, and a store-of-value asset. The fee illustration is conditional, not a reported run-rate: if Solana eventually processed 1 billion payments a day at 1 cent per transaction, that would be $3.65 billion in fees a year. He says transaction volume was continuing to grow, citing Blockworks Research, without putting the chart’s levels into the prose. If these assets have value, he concludes, the reason may be very different from what investors originally expected.
For applications, the businesses that capture the most value are those with at least one of the three moats. Distribution means a direct customer relationship that is hard to migrate; Robinhood and Hyperliquid are his examples. Capital means a balance sheet that can absorb losses. Information means the ability to underwrite risks others cannot. However good models become, all three are much harder to copy than software.
On the instrument, Multicoin says it does not think it matters whether value flows to equity or to a token, and that value will flow to both. The essay says recent SEC guidance and rule proposals have mapped compliant paths for tokens to capture value, without naming those documents, and states that the firm fully intends to invest in those opportunities. What it says actually matters is whether a business — token or equity — controls something scarce, has pricing power because of that, and can turn it into investor returns, whatever the wrapper. As more financial activity moves onchain, the gap between protocols with a moat and protocols that are only software widens. Applebaum describes the work of a large investor in the sector as sorting which projects in the stack have these moats and can keep them.
The incumbent objection, and the wedge he does not call a moat
He then takes the obvious counterargument seriously. If software is becoming free and the moats are the expensive part, incumbents should win. Robinhood has the customers. Goldman Sachs, he suggests, has more capital than any DeFi prime broker may ever have. Moody’s has the data and the licenses.
The startup advantage he keeps is a willingness to take risks incumbents will not. AI cuts both ways. The same tools that would let Robinhood ship a DEX over a weekend let a three-person startup do it. As the cost of building a credible product falls, the opening is markets and customers the incumbent will not pursue.
The case studies are his evidence for that wedge. They are company narratives inside an investment essay, not separate audits of adoption.
- Ethena built a synthetic dollar around delta-neutral hedging. The basis trade is a strategy traditional firms understand, he writes, but could not or would not bring to crypto exchanges. Ethena had scaled it to $5.4 billion of AUM.
- Pump.fun and fomo created new trading experiences in memecoins, a novel asset class, and built substantial distribution around that wedge. He calls them two of the largest success stories of the crypto cycle as of the essay.
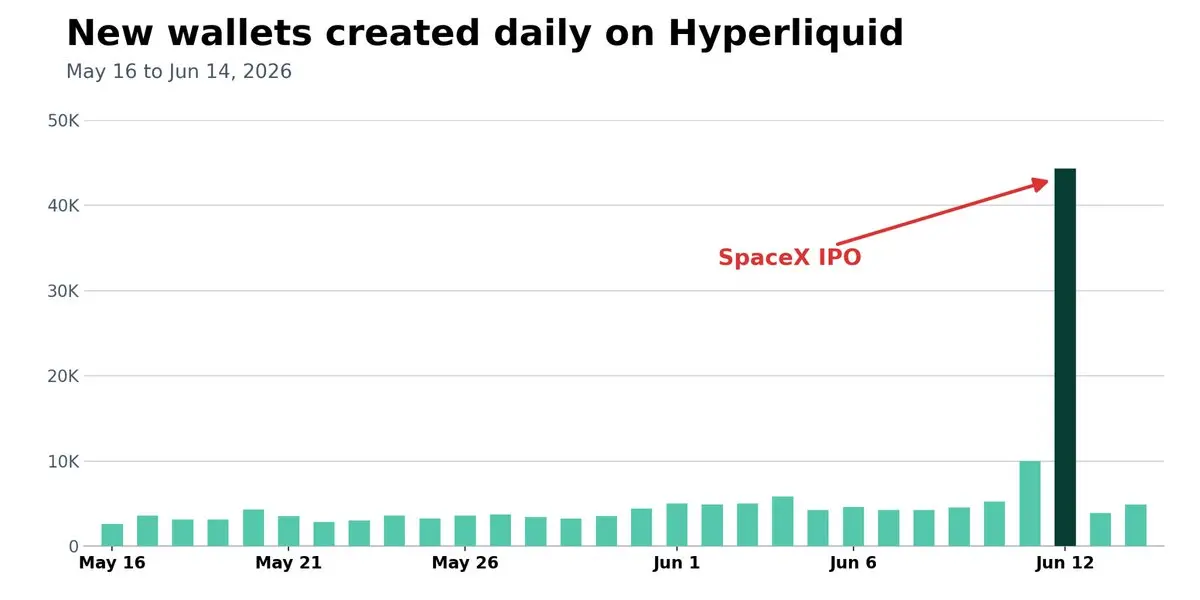
- Hyperliquid entered a derivatives market dominated by Binance, Bybit, and OKX and took share quickly. It was also listing perpetuals on pre-IPO companies such as OpenAI and Anthropic, which he says traditional exchanges will not do. Those markets attracted new traders and liquidity. He points to wallets created on the day of the SpaceX IPO, citing HyperTracker, without putting wallet counts in the text.
- On capital, Project 0 finances DeFi collateral that traditional prime brokers will not accept as lending collateral. On proprietary data, USD.ai can underwrite GPU-backed loans, an asset class he says banks have almost no experience with.
The common thread, as he draws it, is markets incumbents are not serving, whether because of regulation, operational complexity, reputational risk, or because the opportunity looked too small. For startups, he says, there will always be openings to compete asymmetrically, as throughout crypto’s history, and he expects that to continue.
That is why he finds the combination of AI and DeFi compelling. AI sharply lowers the cost of building financial products. DeFi lets a startup reach customers and obtain capital without rebuilding the entire financial stack. Risk appetite, he adds, is not itself a durable moat. Regulation catches up, and once a market is proven, incumbents follow. The spot bitcoin market is his example. A startup does not need a moat on day one. It needs an opening incumbents will not pursue, and enough time to turn that opening into one or more of the three moats, and then compound from there.
What the essay claims, and what it does not show
The close restates the thesis from November 2026. Over the following decade, in Multicoin’s belief, trillions of dollars of financial activity move onchain, and AI makes products that serve that activity easier to build than before. Software becomes commoditized. Customers, capital, and proprietary data do not. The businesses that control them have pricing power. That is why the firm says it is bullish on the next generation of DeFi companies: as AI developer tools spread, startups can compete with incumbents faster and more cheaply, and a new company that establishes one of these moats can build a very durable business. Code can be forked and generated with the latest and strongest model. The moats cannot simply be generated, and that gap is the opportunity Multicoin says it is underwriting as a crypto investor.
Read as a sector narrative, the essay is a map of boundaries rather than a set of interchangeable tokens. It separates attention and build cost — a model can draft a venue, a front end, or a port across chains — from control of balances, from a balance sheet that absorbs losses, and from non-public underwriting data. Several load-bearing figures are the author’s citations and characterizations as carried by ChainCatcher, including Tether’s interest income, the Hyperliquid–USDC economics, curator assets and fees, Ethena’s AUM, and the Binance loss and net outflow. They are not re-derived here. The Solana fee math is an illustration, not a reported run-rate. Nothing in the framework makes an isolated listing, a new chain, or a new coding demo evidence that capital is rotating into a whole category.
Original essay by Spencer Applebaum, general partner and co-head of venture at Multicoin Capital, published by ChainCatcher on November 11, 2026, at 09:27 (UTC+8), compiled by 谷昱 (Gu Yu): https://www.chaincatcher.com/article/2303563