On November 9, 2026, the Wall Street Journal reported that the New York Stock Exchange said its planned 24/7 tokenized-securities platform would settle tokenized stocks only on Avalanche. The same day, Ava Labs said Avalanche would provide the core ledger technology for the clearing company of that NYSE-linked platform, and NYSE pre-market materials also confirmed the arrangement. What follows is drawn from a November 10, 2026 account by Sanqing for Foresight News, published by Odaily—not a later update on whether the venue launched.
A permissioned ledger, not the public chain
The platform was described as an alternative trading system, aimed at a fourth-quarter 2026 launch and still awaiting regulatory approval at the time of that reporting.
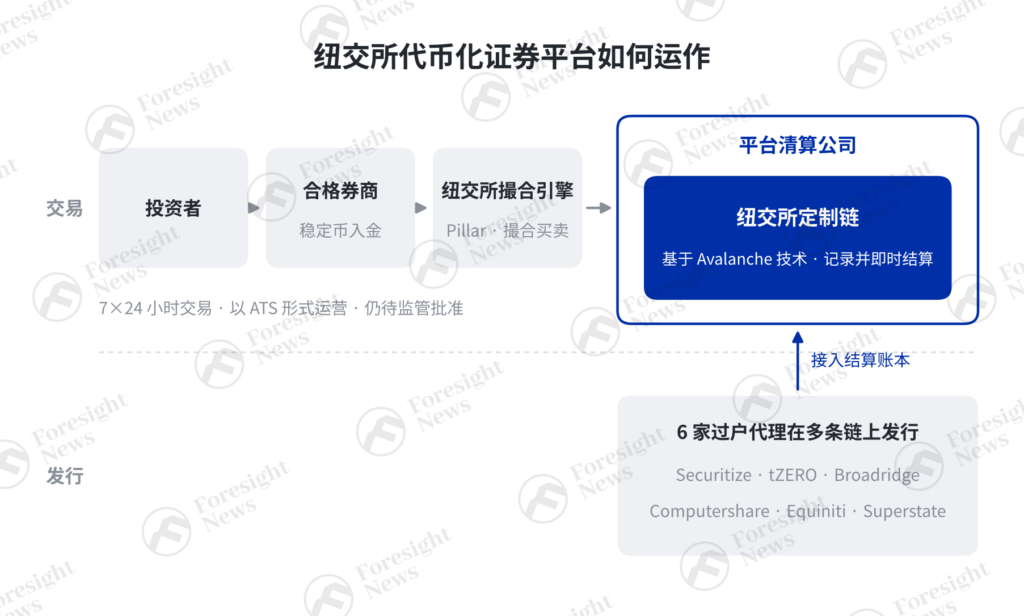
Under the November 9 design, matching would stay on NYSE’s existing Pillar engine. After a trade, the platform’s clearing company would settle immediately on an Avalanche ledger, and investors could fund accounts with stablecoins.
John Nahas, Ava Labs’ chief business officer, said in an interview that NYSE would not settle on Avalanche’s public chain. It would run a blockchain based on Avalanche technology and tailored to regulatory requirements.
Issuance spread out, settlement pulled in
On November 2, 2026—a week earlier—NYSE set out the issuance side. Beyond Securitize and tZERO, it named Broadridge, Computershare, Equiniti, and Superstate as transfer agents, taking the partner count to six. Tokens would be of two kinds: issued by a custodian, or issued by the issuer itself. Both were described as interchangeable with conventional shares, with the same dividend and voting rights.
Dennis Lee, NYSE’s head of digital issuance, said the platform could support stock issued on multiple chains, but the ledger that records and settles trades had to be fast and reliable, able to control participants, predictable in cost, and supported by a large developer community. He said Avalanche met those tests. The resulting split is issuance across several transfer agents and chains, and settlement gathered onto a chain NYSE would operate.
How the choice narrowed
NYSE said on January 19, 2026 that it was building the platform and seeking regulatory approval. On August 31, parent Intercontinental Exchange signed a memorandum of understanding with tZERO. At the Avalanche Summit that September, Ava Labs president Charley Cooper said NYSE had been testing Avalanche for about a year, without announcing a selection. On NYSE Live on November 9, Cooper said the step being confirmed was a production deployment, not another pilot.
The January notice had said the platform could support multiple chains for settlement and custody. By November, the public position had narrowed to Avalanche alone. Kevin Tyrrell, NYSE’s chief product officer, said the exchange tested several vendors and weighed speed, throughput, and the ability to support a controlled network and compliance requirements. Nahas said the technical, commercial, and ecosystem review took more than a year.
Why the C-Chain was ruled out
Of the conditions Lee listed, control of participants is the one that decides the architecture. Parties to stock settlement must be admitted. Avalanche’s mainnet C-Chain is public—anyone can connect—so it does not meet that bar.
The custom chain corresponds to the self-built L1 model, formerly called a Subnet, that Avalanche introduced after the Etna upgrade (ACP-77). An institution’s L1 runs independently of mainnet and manages its own validator set. It can be permissioned. Validators do not have to stake 2,000 AVAX first in order to become mainnet validators; they pay a fixed monthly fee, which is what makes cost predictable.
In the announcement, Ava Labs CEO Emin Gün Sirer said this dedicated infrastructure could still connect to a wider set of assets and liquidity, and that Avalanche L1s can exchange native cross-chain messages. That is a statement about design, not a figure for assets already moving through the NYSE venue.
What was already counted as Avalanche RWA
rwa.xyz data cited as of November 9, 2026 put Avalanche’s distributed RWA—tokens that can move freely between wallets—at $1.43 billion, represented RWA—ownership recorded on-chain only—at $11.4 billion, and stablecoin market value at $795 million. Those are measures of assets associated with the network. They are not turnover on an exchange platform that, as of the report, had not launched.
The token move, and what the announcements left out
After the news, Bitget prices cited in the original piece showed AVAX reaching a high of 9.01 USDT and printing 8.627 USDT at the time of writing, a 24-hour gain of 6.86%. That is an attention print.
Neither the Ava Labs announcement nor the NYSE statement mentioned a role for the AVAX token in settlement, fees, or staking. Under the custom-L1 mechanism, the direct AVAX inflow is the ongoing validator fee. Avalanche documentation, as summarized in the report, says that when an L1 has fewer than 10,000 validators, each validator pays about 1.33 AVAX a month. Those tokens are burned. The fee is not linked to how many trades settle or how large they are. Fees inside the L1 can be denominated in a token the operator chooses.
A capture gap the foundation had already described
On July 30, 2026, when the Avalanche Foundation set out an economic research agenda, it acknowledged that value created in the ecosystem does not automatically flow to the AVAX that secures the network. Chief investment officer Matias Antonio called that the core problem the foundation was trying to solve.
Estimates the foundation published on August 12 said that, in the on-chain activity it counted, the main AVAX capture was C-Chain fee burns: about $23.5 million cumulative since the start of 2024, excluding L1 validator fees. Sharing of L1 revenue was still under study, with no mechanism decided.
The latest month in that estimate was June. Nominal on-chain GCP—likened to an on-chain GDP—was $3.1 million. Returns to holders from assets such as tokenized funds were $2.7 million. Earnings issuers took from reserve assets were $6.9 million. The foundation’s view was that those latter two streams were, at the time, basically not contributing to AVAX value capture.
The improvements it listed were all still research: ACP-283, under which validators would vote to adjust the gas price; ACP-67, a protocol-owned stablecoin; and revenue sharing from applications and L1s.
On the mechanism as described, settlement on NYSE’s custom chain would also sit outside AVAX capture. Only the validator fee would touch AVAX. The C-Chain, described as the main capture channel then in place, was not large on fees either. DefiLlama data cited for November 9 put Avalanche C-Chain fees at about $26,500.
The day the news was published, the Avalanche Foundation posted that it would use the economic research agenda to track the platform’s activity and its place in the Avalanche economy. Tracking is not a fee link.
Narrative, participants, and what was not yet adoption
The story being told is an institutional real-world-asset story: a major exchange selecting one settlement stack for tokenized equities that are supposed to carry ordinary dividend and voting rights, on a clock that runs seven days a week. The participants named in the reporting are NYSE and its parent ICE, Ava Labs, and six transfer agents. The proposed use is continuous trading, matched on Pillar and settled on a permissioned Avalanche-based L1, funded with stablecoins.
As of the November 10, 2026 report, measurable adoption of that venue was still in front of it. Regulatory approval was outstanding, and a fourth-quarter target is a schedule. The day’s AVAX price change shows attention. On the terms of both announcements, it does not show that equity settlement volume would accrue to the token. Category labels do not make every Avalanche-linked asset, or AVAX itself, equivalent to a share of NYSE flow.
Original article: Odaily, November 10, 2026, based on Sanqing, Foresight News.